Bond duration mechanics and 4 proven rules that prevent devastating portfolio losses
Maturity dates tell you when a bond terminates, but duration reveals how violently it reacts to shifting rates. Discover the cash flow physics that protect fixed income capital from severe market drawdowns.
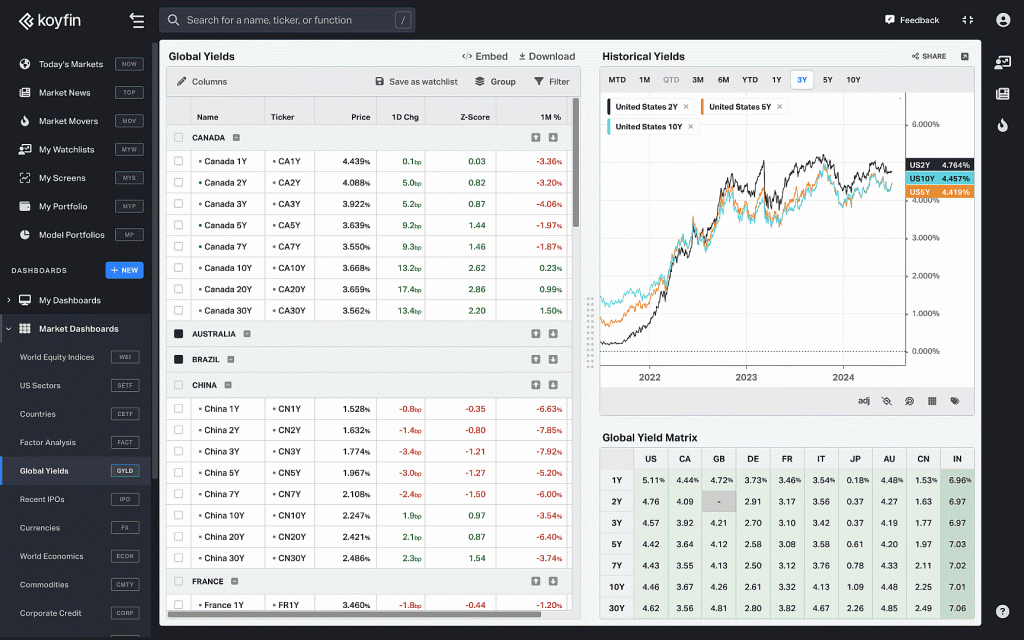
Understanding bond duration mechanics separates investors who merely hope for stability from those who deliberately engineer it. Most market participants treat bonds like simple deposit accounts with a guaranteed finish line. They buy an instrument with a ten-year maturity, look at the stated coupon yield, and assume their principal is fundamentally insulated from systemic turmoil. This assumption holds until monetary policy shifts, benchmark yields climb, and their supposedly safe holdings suffer painful, double-digit drawdowns. The problem is not that fixed income failed to function, but that the investor misunderstood what actually measures interest rate risk.
Maturity measures calendar time, whereas duration measures economic time. A portfolio of bonds maturing in twenty years does not behave uniformly; a zero-coupon issue swings with ferocious volatility at the slightest whisper of a rate adjustment, while an ultra-high coupon security floats along with calm resilience. To control capital preservation across changing economic cycles, an allocator must look past the terminal date and calculate the precise fulcrum where cash flows balance against time.
When you strip away complex quantitative jargon, duration is simply the weighted average arrival time of every dollar a security will ever pay you. Every semi-annual interest payment pulls your invested capital forward into the present, insulating you from future macro volatility. Every payment pushed decades down the line exposes your wealth to the compounding erosion of shifting discount rates. Grasping this reality transforms how you evaluate credit, construct asset allocations, and protect generational wealth.
How Cash Flow Timing Dictates Real Market Volatility
The mathematical foundation of fixed income hinges on present value discounting. When discount rates rise, cash flows scheduled for the distant horizon lose purchasing power exponentially faster than cash flows arriving tomorrow morning. Because of this dynamic, exploring bond duration mechanics reveals that a bond’s real sensitivity to interest rate fluctuations is entirely determined by its cash flow structure. This relationship was first formalized by Frederick Macaulay, who proved that a bond’s effective lifespan is virtually always shorter than its stated legal maturity, provided it pays an interim coupon.
Think of duration as the balancing point on a physical seesaw. If you place a heavy cash payment at the twenty-year mark with zero payments along the plank, the fulcrum must sit far to the right to balance the weight. If, instead, you drop regular, heavy cash distributions across years one through nineteen, that fulcrum moves rapidly toward the present. Modified duration translates that balance point into a direct operational metric, telling you approximately how much the bond’s market price will rise or fall for every one percentage point shift in prevailing interest rates.
This dynamic creates stark contrasts between instruments that appear identical at first glance. A ten-year government bond with a negligible yield might carry a modified duration of roughly nine years, meaning a two-percentage-point jump in benchmark rates will strip eighteen percent off its market value overnight. Conversely, a ten-year corporate issue paying an eight percent coupon continuously distributes cash back into the owner’s hands, dropping its duration down to roughly six and a half years. The coupon acts as a mechanical dampener against market volatility.
Four Proven Rules That Shield Portfolios From Sudden Interest Rate Spikes
Mastering bond duration mechanics demands more than reciting textbook definitions. It requires applying strict structural parameters to portfolio construction so that rate volatility works for you rather than against your balance sheet. By treating duration as an active risk parameter rather than a passive byproduct of fund purchases, you establish structural defenses that withstand even the most aggressive macro shocks.
Match Asset Duration to Known Liability Horizons
The first defense against rate risk is classical portfolio immunization. If you know you require liquidity to settle a major obligation or fund an expenditure seven years from today, holding cash or seven-year maturity debt creates an unintended timing mismatch. Cash leaves you exposed to reinvestment risk if rates drop, while a seven-year coupon bond carries a duration of roughly five and a half years, meaning your funds will liquidate before or after the true inflection point of your need.
True immunization occurs when the modified duration of your bond portfolio matches the exact time horizon of your liabilities. When duration aligns with your timeline, the opposing forces of price risk and reinvestment risk cancel each other out. If interest rates rise, the capital loss on your paper value is mechanically offset by the higher yields earned on reinvested interim coupons over that seven-year period. If rates plunge, capital gains offset the lower coupon yield on new purchases. The aggregate terminal value remains remarkably stable.
Harness Convexity as an Asymmetric Downside Buffer
Modified duration provides a linear estimate of price changes, but the real relationship between bond prices and yields is curved. Investors who internalize bond duration mechanics understand that price changes are not linear, and this natural curvature is known as convexity. When yields drop, a standard bond’s price rises faster than duration alone predicts; when yields rise, the price drops more slowly than duration suggests. Positive convexity is the ultimate mathematical tailwind for fixed income investors.
To maximize this structural advantage, favor instruments with pristine positive convexity, such as non-callable sovereign debt and premium investment-grade paper. Steer away from securities with negative convexity, such as callable debt, where the issuer retains the legal right to buy back the bond when rates plummet. By deliberately assembling a portfolio with superior convexity, you ensure that your downside losses are mechanically compressed during monetary tightening cycles, while your upside upside participation expands automatically when yields compress.
Construct Barbells to Neutralize Yield Curve Twists
Yield curves rarely move in tidy, parallel shifts across all maturities. Short-term rates might skyrocket due to central bank liquidity tightening, while long-term yields remain anchored by expectations of sluggish economic growth, causing the curve to invert. A standard bullet portfolio—concentrating all holdings in intermediate five-to-seven-year issues—takes the full brunt of structural curve shifts without offering tactical flexibility.
A barbell strategy splits allocations between short-duration cash equivalents and long-duration zero-coupon or low-coupon bonds. The ultra-short paper provides immediate liquidity and captures surging yields on rolling reinvestments without suffering principal destruction. Meanwhile, the long-duration sleeve provides powerful capital preservation leverage against deflationary tail events. This split construction enables you to match the average duration of a middle-market benchmark while possessing dramatically superior convexity and rebalancing liquidity.
Audit Negative Convexity and Embedded Prepayment Options
High yields often disguise asymmetric downside risks. Mortgage-backed securities and callable corporate bonds offer attractive headline spreads, but they house structural traps known as embedded options. When interest rates drop, homeowners refinance and corporate treasurers call in high-interest paper, forcing investors to receive their principal back precisely when reinvestment opportunities are most punitive. This dynamic creates severe negative convexity.
Conversely, when interest rates march upward, prepayments dry up entirely. What an investor believed was a seven-year average life mortgage pool suddenly extends into a twenty-year paper commitment, locking them into below-market yields just as inflation accelerates. Conduct an exhaustive audit of your fixed income assets to uncover embedded call structures. Unless you are receiving an outsized risk premium to justify holding negative convexity, insist on unencumbered, option-free structures that keep duration steady through the economic cycle.
The Dangerous Mirage of Yield Without Duration Awareness
When capital allocators ignore bond duration mechanics, they routinely confuse yield with safety. In tranquil markets, yield appears to be the only metric that matters. Investors sift through bond funds or credit opportunities looking for the highest nominal distribution rate, completely blind to the fact that achieving an extra fifty basis points of annual income often requires extending duration into territory that exposes the portfolio to massive capital drawdowns.
Consider what happens during a rapid tightening regime. A fund yielding four percent with an average duration of twelve years will suffer a twelve percent capital decline if yields climb by a single percentage point. It takes three full years of uncompromised coupon payments just to recoup the paper losses incurred from that modest macro shift. Chasing an incremental half-percent of return by walking blind into massive duration exposure is the financial equivalent of picking up pennies in front of a steamroller.
Just as culinary mastery relies on deep cellular physics rather than surface temperature—much like how dry brining mechanics and 4 proven rules that prevent tough chewy meat transform raw ingredients through patience—fixed income preservation demands an uncompromising respect for time horizons over nominal interest rates. The stated yield on a brokerage screen is merely a surface artifact; the cash flow distribution schedule is the underlying engine that dictates whether you preserve capital or incinerate it.
Institutional Portfolio Immunization and Curve Positioning
Modern asset managers use bond duration mechanics to execute portfolio immunization with surgical precision. Rather than making speculative bets on the timing or magnitude of central bank decisions, institutional desks manage dollar duration, often referred to as DV01 or the dollar value of a basis point. This metric establishes exactly how many thousands or millions of dollars a portfolio gains or loses for every basis point change across each maturity segment of the curve.
By mapping out key rate durations, risk managers pinpoint vulnerabilities at specific maturities along the curve. For instance, a portfolio might have an aggregate duration of five years, but an audit might reveal that all the interest rate risk is concentrated in the thirty-year segment, balanced out by massive cash holdings. That fund will react violently to a steepening curve even though its headline duration metric seems conservative. Leading research from the CFA Institute foundational fixed income research underscores that decomposition of duration across individual curve segments is the only way to avoid catastrophic positioning traps during structural regime changes.
Professional treasury teams continuously rebalance cash allocations and coupon receipts against target duration profiles. When yields peak, institutional allocators deliberately extend duration by swapping floating-rate notes for long-dated, fixed-coupon sovereign bonds. When yields sit at generational lows, they mechanically contract portfolio duration by rotating into ultra-short instruments and floating debt. They do not treat duration as a static number, but as an active dial that expands and contracts in lockstep with the broad credit environment.
Mastering Capital Preservation Through Structural Cash Flow Discipline
Grasping bond duration mechanics transforms fixed income from an unpredictable risk into a calibrated engine for capital defense. The market will always experience periods of stubborn inflation, aggressive policy tightening, and unexpected credit freezes. Trying to forecast the exact month these cycles turn is a fool’s errand that leaves portfolios exposed to devastating miscalculations.
True financial resilience lies in structural design. When you understand how cash flow intervals interact with discount rates, you stop viewing bonds as promises written on paper and start treating them as time-discounted cash streams. You stop blindly buying intermediate mutual funds with unmanaged duration profiles, and you start deliberately building liability-matched portfolios, harvesting positive convexity, and deploying barbell allocations that thrive across volatile yield curve shifts.
Capital preservation does not mean hiding in cash, nor does it mean accepting whatever nominal yield a debt fund happens to post. It demands active command of the calendar, mathematical timing of your capital returns, and total control over your portfolio’s sensitivity to interest rate shifts. Once you master the structural physics of cash flows, you build a fortress portfolio capable of surviving any macro storm.