Working capital cycle mechanics and 4 proven rules that prevent costly liquidity traps
A business can produce soaring accounting profits while simultaneously careening into bankruptcy. Understanding cash conversion velocity reveals how working capital either fuels sustainable expansion or triggers a sudden balance sheet freeze.
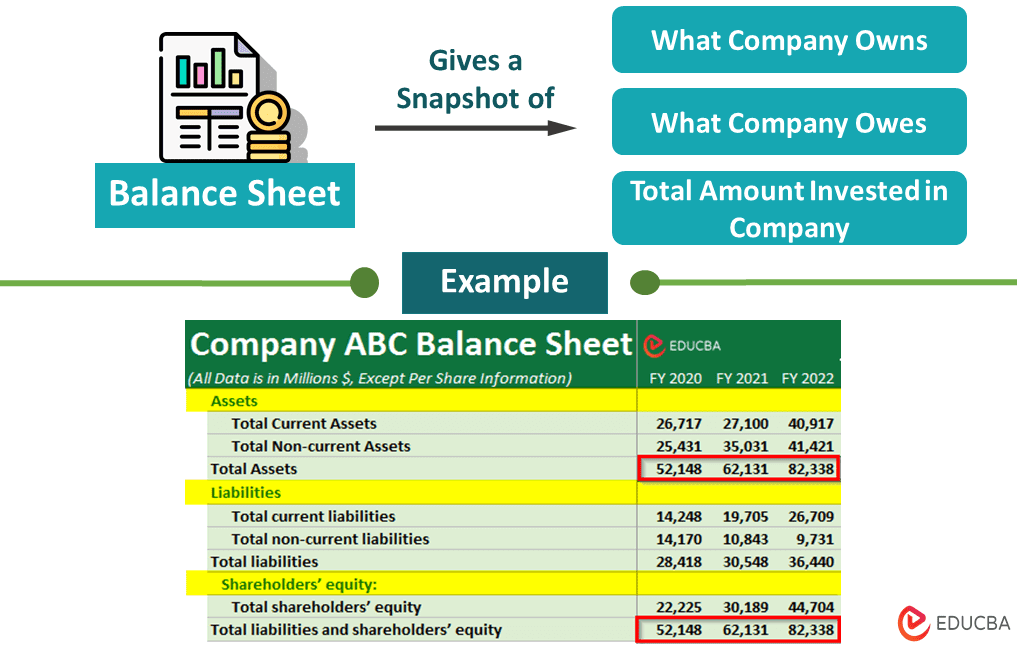
Understanding working capital cycle mechanics separates resilient enterprises from fast-growing businesses that quietly run out of cash during periods of rapid expansion. Profitability recorded on an income statement is an opinion formed through accrual accounting conventions, but liquidity in a commercial bank account remains an unyielding physical reality. When an executive team secures record sales contracts, celebration often masks an impending financial drought. Delivering products requires purchasing raw materials, paying factory wages, storing finished stock, and waiting weeks or months for customers to settle their invoices.
This operational delay between outbound expenditures and inbound receipts forms the fundamental pulse of enterprise commerce. When financial analysts dissect corporate balance sheets, they frequently discover that working capital cycle mechanics govern day-to-day survival far more acutely than operating margins. An enterprise can report record quarterly net income while simultaneously sliding toward an emergency credit draw. Without deep visibility into the hydraulic motion of working capital, growth does not compound corporate wealth; it accelerates structural insolvency.
The brutal reality of growing broke while looking profitable on paper
The paradox of profitable failure is one of the most persistent hazards in corporate finance. It stems directly from the mechanics of overtrading. When a manufacturing firm or distributor experiences a sudden 80 percent surge in customer orders, operating overhead does not wait for invoice collection. Suppliers demand immediate payment for increased raw materials, assembly lines demand overtime wages, and shipping logistics demand upfront freight charges. Meanwhile, the revenue from those surging sales sits frozen in accounts receivable under standard thirty, sixty, or ninety-day payment terms.
Every additional dollar of uncollected revenue consumes tangible liquidity. If an organization lacks sufficient cash reserves or revolving credit lines to bridge this widening gap, the balance sheet snaps under its own momentum. The enterprise finds itself unable to meet payroll or tax liabilities despite boasting full order books and pristine gross margins. Bankruptcy courts routinely handle cases of companies that did not fail because their products lacked demand, but because their cash conversion velocity could not keep pace with their top-line expansion.
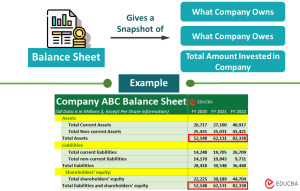
The underlying danger is structural complacency. Leaders look at an upward-trending revenue curve and assume balance sheet health naturally follows. In truth, top-line acceleration acts as a magnifying glass. If an operational engine requires sixty cents of tied-up working capital to generate one dollar of incremental sales, doubling sales volume demands an immediate injection of capital. When that cash is not readily accessible from free cash flows or debt facilities, the organization enters a liquidity vacuum.
The hydraulic levers behind the cash conversion equation
The mathematical framework underpinning this reality is the cash conversion cycle, expressed in days. The three core ratios that define working capital cycle mechanics operate as interconnected hydraulic chambers. When one chamber expands, liquid capital is either released into operations or locked deep inside operational inventory and customer credit.
The first lever is Days Sales of Inventory, measuring how long manufactured goods or procured wholesale stock sit in warehouses before being sold. Capital bound to warehouse shelving generates zero yield and steadily incurs holding expenses, including facility rent, insurance, handling labor, spoilage, and obsolescence risks. The second lever is Days Sales Outstanding, which measures the average number of days required to collect payment after a sale occurs. Extended collection cycles represent an interest-free loan funded entirely by the vendor, transferring capital power straight to the client.
The third lever acts as a counterweight: Days Payable Outstanding. This metric reveals how long an organization retains its own cash before paying trade suppliers. Lengthening payable days preserves internal liquidity, effectively funding daily operations using supplier credit. As demonstrated in corporate finance research compiled by NYU Stern, working capital requirements fluctuate radically across industries, demonstrating that capital efficiency is deeply tied to structural supply chain negotiation power rather than balance sheet size alone.
Four operational rules that protect corporate liquidity
Applying rigorous operational discipline to working capital cycle mechanics requires balancing commercial leverage against liquidity buffers. These four foundational practices protect an organization from balance sheet erosion while optimizing ongoing capital productivity.
Rule 1: Compress inventory velocity without triggering catastrophic stockouts
Treating inventory as safety padding rather than stranded capital is an operational trap. Excess safety stock quietly degrades balance sheet health by soaking up liquid capital that could otherwise fund strategic expansion or de-risk debt covenants. Eliminating this inertia requires transitioning from blunt historical forecasts toward pull-based manufacturing and localized demand sensing. Categorizing stock using tiered turnover velocity allows procurement managers to run aggressive, lean stocking schedules on high-predictability items while reserving capital buffers strictly for volatile, critical stock. Every day shaved off storage duration directly liberates cash without depressing operational throughput.
Rule 2: Enforce dynamic receivable covenants before invoices age into bad debt
To optimize working capital cycle mechanics on the collection side, companies must align invoice workflows with strict credit terms. Unmonitored receivables quietly decay over time. As an unpaid invoice crosses sixty and ninety-day thresholds, the statistical probability of full recovery drops precipitously. Finance teams must eliminate systemic invoicing delays by automating billing generation at the exact moment of delivery rather than at month-end batch processing. Furthermore, offering calibrated discounts for rapid payment incentivizes client treasuries to liquidate obligations early, generating instant liquidity that far outweighs the minor margin concession.
Rule 3: Optimize payable terms without fracturing vendor supply resilience
Maximizing payable days sounds mathematically attractive, but unilateral payment delays create hidden supply chain fragility. Pushing key vendors beyond agreed contractual boundaries forces smaller suppliers into liquidity crises, causing delivery bottlenecks, reduced material quality, or sudden vendor attrition. Sustainable payable optimization depends on formalized, mutually beneficial agreements. Implementing supply chain finance programs allows institutional lenders to pay suppliers early based on the buyer credit profile, while the buyer retains extended payable terms. This preserves crucial internal cash reserves while securing primary supplier solvency.
Rule 4: Exploit negative working capital float without building fragile dependencies
Navigating the extreme end of working capital cycle mechanics means understanding how negative cash conversion creates a self-funding growth engine. Certain business models collect customer cash instantly at point of sale while maintaining ninety-day vendor terms. In these environments, operational growth produces cash surpluses rather than capital deficits because customers finance supplier obligations. However, treating this vendor float as permanent operating equity is hazardous. If sales velocity decelerates suddenly, accounts payable liabilities come due immediately while incoming cash receipts drop, producing a rapid liquidity crunch if unearned revenue has already been spent on fixed operational overhead.
Why valuation multiples collapse when operating cash fails to materialize
Equity markets and institutional buyers inevitably penalize companies that deliver accounting earnings unsupported by operating cash conversion. When working capital expands faster than operating earnings, Free Cash Flow to the Firm drops. This gap signals to investors that reported earnings are of poor quality, dragged down by uncollected receivables or inventory build-ups that may ultimately require catastrophic write-downs.
Investors who run a rigorous discounted cash flow valuation and 4 proven rules that prevent costly investment traps quickly learn that an unmanaged working capital spike drains free cash flow instantly. In financial modeling, changes in non-cash working capital subtract directly from operating cash flow. If a company generates one hundred million dollars in operating earnings but absorbs eighty million dollars to fund bloated inventory and unpaid trade bills, its intrinsic value is fundamentally compromised. Market multiples contract sharply when capital allocators realize that top-line growth is perpetually cannibalizing liquidity.
Diagnostic stress tests that protect enterprise balance sheets
Protecting a commercial enterprise against sudden liquidity shortfalls requires proactive stress testing rather than backward-looking post-mortems. Finance teams should run sensitivity analyses on cash conversion variables at least once every quarter. What happens to total liquidity if the top five enterprise clients extend payment terms by fifteen days? What happens to cash reserves if raw material delivery delays force a 20 percent increase in safety stock requirements?
Simulating these operational shifts exposes vulnerabilities long before a credit line reaches maximum capacity. It transforms working capital from a passive accounting byproduct into an active strategic shield. Companies that systematically monitor these metrics construct dynamic liquidity reserves, renegotiate covenants from positions of strength, and preserve operating agility during economic downturns. Ultimately, mastering working capital cycle mechanics shields expanding firms from the fatal trap of growing broke, ensuring that operational success translates directly into enduring financial stability.