IonQ Stock Faces 4 Critical Market Pressures After Painful 50 Percent Plunge
A punishing 50 percent drop over the past year has forced market observers to re-examine IonQ’s commercial viability. Here is how architectural rivalries and strategic acquisitions are shaping the next quantum inflection point.
Navigating the volatile frontier of modern computing has proven challenging, as IonQ stock plunged by roughly 50.3 percent over the past year. According to market research from Trefis published through Yahoo Finance, that steep contraction unfolded even as high-performance enterprise tech caught historic tailwinds. Investors seeking the next computational hardware paradigm following the artificial intelligence boom have increasingly looked toward quantum architecture, yet commercialization timelines remain intensely contested across Wall Street trading desks.
The sudden divergence between broader enterprise technology euphoria and pure-play quantum valuations reveals fundamental tensions in capital allocation. While hyperscale enterprise software players ride expanding operating margins, pure-play quantum platforms confront extended research and development cycles, high cash consumption rates, and architectural bifurcations. For investors evaluating whether IonQ stock represents an undervalued turnaround play or a speculative trap, dissecting the structural mechanics beneath the share price drop is essential.
The Steep Realities Behind the Quantum Market Divergence
The broader technology sector spent the past eighteen months pricing in immediate productivity gains from enterprise compute, creating a high bar for capital-intensive frontier labs. Market analyses from The Motley Fool emphasize that retail and institutional traders initially grouped quantum hardware directly alongside accelerated silicon processors. However, unlike graphics processing units that convert directly into recurring enterprise cloud billing today, general-purpose quantum computing remains an iterative enterprise deployment model.
This timing mismatch created friction for market participants expecting near-term exponential revenue trajectories. When hardware delivery dates stretch across multi-year roadmaps, speculative multiples contract violently. In complex enterprise ecosystems, strategic positioning matters just as much as endurance; much like how Bicycle drafting mechanics reveal 4 proven secrets to conquer punishing cycling fatigue, market leaders must streamline friction to survive protracted macroeconomic headwinds. Pure-play developers cannot simply draft behind artificial intelligence momentum without demonstrating distinct commercial utility, verifiable gate fidelity, and stable customer contracts.
Trapped Ions Against Superconductors and Annealing Architecture
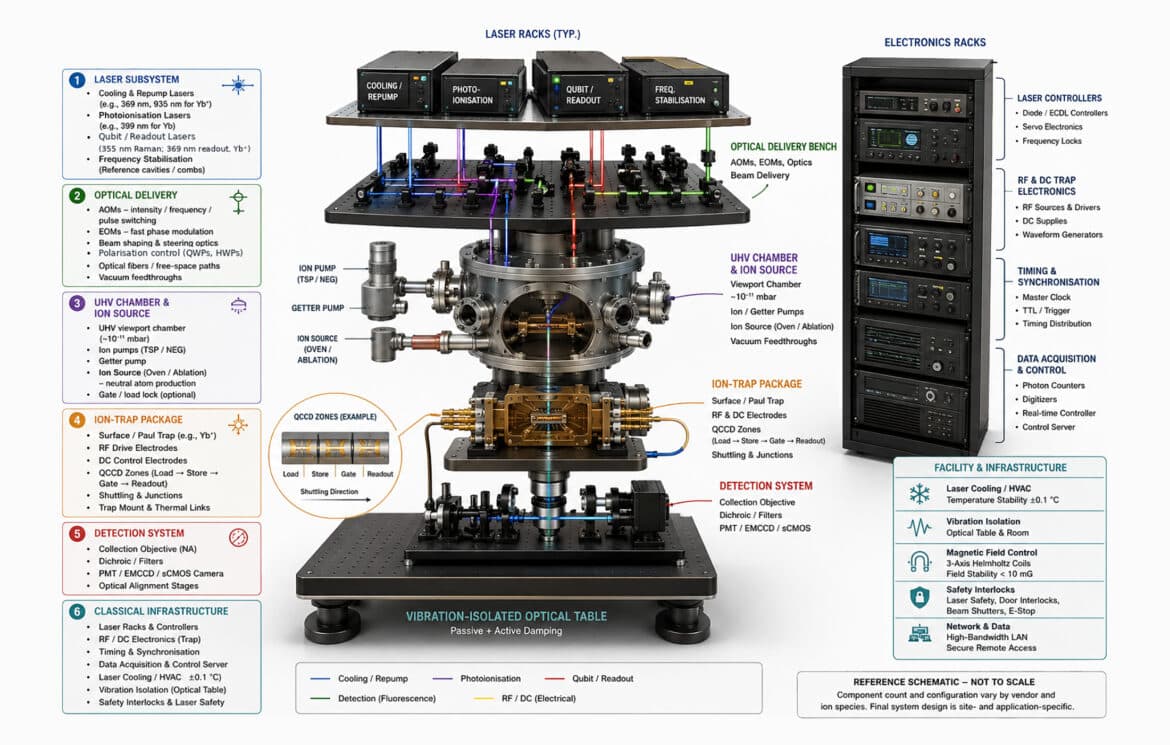
To evaluate the company’s valuation trajectory, market analysts inspect the engineering foundation separating competing platforms. As documented in a technical breakdown by 24/7 Wall St., hardware divergence dictates corporate survival. IonQ builds systems centered on trapped-ion architecture, which suspends individual charged atomic ions in electromagnetic fields and manipulates their quantum states using precision laser optical systems. This methodology prioritizes high gate fidelities, extended coherence times, and room-temperature operation at the chip level, avoiding the massive cryogenic refrigeration dilution refrigerators required by competing approaches.
Yet this approach carries inherent engineering trade-offs. Trapped-ion systems face distinct gate speed limitations when compared to the lightning-fast operational switching times of superconducting circuits championed by competitors. Furthermore, scaling up the absolute physical qubit count within a single ion trap introduces optical alignment hurdles, prompting the need for photonic interconnects to link modular traps together. Competitors employing alternative physics models argue their paths offer faster scaling curves, positioning IonQ stock as a distinct trapped-ion pure-play within a volatile sector.
4 Crucial Forces Reshaping Commercial Quantum Viability
The structural repricing observed across trading venues reflects four specific operational pressures impacting balance sheets, competitive standing, and technical validation across global enterprise markets.
The Painful 50 Percent Valuation Correction
The primary pressure driving market sentiment is the sharp mathematical reset documented by Yahoo Finance and Trefis research, which recorded a 50.3 percent drawdown over a twelve-month window. This valuation compression squeezed earlier multiples that had expanded rapidly during speculative trading cycles. As global interest rates stayed elevated, institutional allocators applied much higher discount rates to pre-profit technology ventures. When future cash flows are discounted aggressively, companies requiring continuous capital expenditure face immediate repricing, forcing management teams to balance aggressive laboratory milestones against financial runway preservation.
Aggressive Corporate Acquisitions and Balance Sheet Strain
Corporate expansion moves intended to consolidate technical dominance have introduced near-term skepticism among market participants. A MarketBeat report syndicated via TradingView highlighted that market bulls balked following mid-October strategic acquisition announcements designed to accelerate system integration and proprietary intellectual property assets. While buying complementary networking or optical components can eliminate engineering bottlenecks, it often involves cash outlays or secondary equity issuance. The market reaction reflected persistent anxieties that IonQ stock could face dilution pressures if balance sheet reserves deplete before revenue scales.
The Intense Rivalry Across Rigetti and D-Wave Systems
The competitive perimeter surrounding commercial quantum installations is growing more crowded and technologically fragmented. An assessment by The Motley Fool comparing early-stage quantum operators highlighted how companies must battle for finite government research grants, commercial pilot projects, and academic supercomputing partnerships. While IonQ advances trapped ions, Rigetti Computing pursues superconducting quantum processing units designed for rapid gate execution, and D-Wave Systems concentrates heavily on quantum annealing tailored specifically for complex industrial optimization challenges.
As 24/7 Wall St. pointed out, D-Wave’s focus on commercial annealing platforms allows it to secure current enterprise optimization contracts for logistics and scheduling problems, even if annealing does not solve universal quantum algorithms. That architectural divergence splits the available capital pool, forcing institutional funds to weigh near-term pragmatic optimization deployment against long-term universal error-corrected computing power when scrutinizing how IonQ stock compares against direct peers like Rigetti Computing.
AI Spillover Momentum Connecting Cloud Giants and Frontier Hardware
Macro enterprise technology roadmaps are converging rapidly toward heterogeneous data centers. The Zacks Analyst Blog recently identified quantum computing alongside surging artificial intelligence spending and semiconductor demand as foundational pillars shaping computing infrastructure through 2027. Zacks highlighted that mega-cap technology stalwarts, including Microsoft and Palantir Technologies, alongside semiconductor memory and fabrication equipment leaders like Micron Technology and Lam Research, are constructing the fundamental backbone of modern data pipelines.
This dynamic presents both an extraordinary opportunity and an execution risk. Hyperscale cloud providers host quantum hardware instances directly within their cloud platforms, offering immediate access to enterprise software developers globally. However, these same cloud titans are financing internal quantum research divisions, meaning pure-play developers must continuously demonstrate that their proprietary trapped-ion processing units deliver measurable performance advantages over internal corporate laboratory designs.
Capital Allocation Across the Long Horizon Toward 2027
Managing research expenditures against enterprise monetization milestones will dictate market resilience over the next three fiscal years. As noted in the Zacks analysis regarding projected 2027 infrastructure spending, modern computing architectures will increasingly blend classical computing, accelerated graphics processing, and specialized quantum coprocessors. Developing universal error-corrected machines requires millions of dollars in continuous capital allocation for precision lasers, ultra-high-vacuum chambers, and specialized control electronics.
The critical financial metric for observers remains operating cash burn relative to cash equivalents. When hardware companies pursue aggressive mergers, acquisitions, and facility expansions, maintaining capital efficiency is paramount. If execution falters or production scaling encounters delays, public equity markets often respond with sharp corrections, creating a complex roadmap where IonQ stock mirrors the classic profile of an early-stage deep-tech bet facing execution milestones.
Evaluating Risk Profiles in Emerging Enterprise Quantum Systems
The long-term path forward for commercial quantum computing hinges on achieving genuine quantum advantage, the threshold where a quantum system solves economically valuable real-world problems significantly faster or cheaper than the most powerful classical supercomputers. Trapped-ion systems boast exceptionally clean qubit fidelity, meaning fewer physical qubits may be required to produce a single stable logical qubit compared to noisier alternative physical substrates. That engineering advantage remains a compelling thesis for technical purists.
Nevertheless, the market has clearly shifted away from valuing pure speculative ambition toward demanding clear engineering execution, disciplined mergers and acquisitions, and tangible commercial revenue growth. As macroeconomic crosscurrents test enterprise technology multiples, investors tracking IonQ stock must separate genuine engineering breakthroughs from promotional exuberance. The path through public equity markets remains demanding, and institutional validation will ultimately depend on delivering scalable, error-corrected computing systems that justify commercial adoption.