Cash conversion cycle mechanics and 4 proven rules that prevent devastating corporate insolvency
Paper profits frequently mask severe cash depletion, luring expanding companies into sudden bankruptcy. Discover how operational working capital engineering transforms inventory, receivables, and payables into an engine for permanent liquidity.
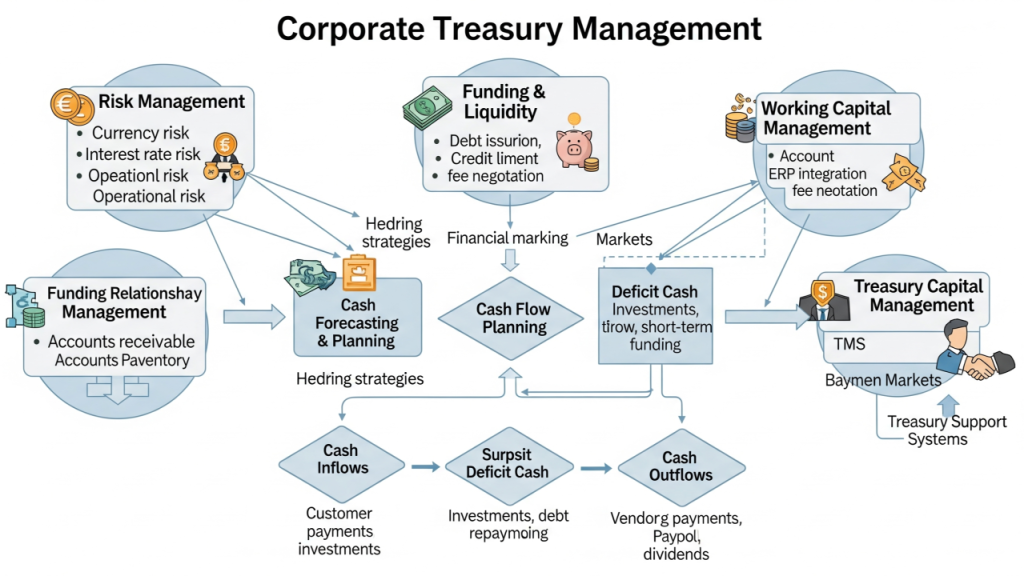
Mastering cash conversion cycle mechanics separates resilient enterprises from fast-growing operations that suddenly collapse into unexpected bankruptcy. On paper, revenue can climb with intoxicating momentum. Glossy pitch decks showcase accelerating top-line expansion, and income statements reflect seemingly healthy operating margins. Yet behind that facade of prosperity, working capital often bleeds out in silent increments. Physical cash evaporates into unpaid invoices, warehouse overflow, and misaligned payment schedules.
Every commercial venture functions like an intricate hydraulic mechanism. If fluid stops circulating through the operational valves, internal pressure drops instantly, grinding critical machinery to a dead halt. Understanding the precise duration required to turn invested cash back into realized liquidity is not an academic chore reserved for corporate controllers. It represents the ultimate dividing line between durable solvency and catastrophic failure.
The Hidden Physics of Operational Cash Traps
Cash conversion—often codified as the cash-to-cash cycle—measures the exact time elapsed from disbursing money for raw inventory to receiving hard currency from customer payments. This progression hinges on three interdependent variables: Days Inventory Outstanding (DIO), Days Sales Outstanding (DSO), and Days Payable Outstanding (DPO). Expressed mathematically, the cycle equals DIO plus DSO minus DPO.
Each variable exerts its own hydraulic force on balance sheet health. Days Inventory Outstanding reflects how long capital sits immobilized in raw materials, work-in-progress components, and finished warehouse stock. Days Sales Outstanding tracks the lag between invoicing a client and seeing verified deposits hit the commercial bank ledger. Days Payable Outstanding dictates how long an enterprise preserves its cash before satisfying supplier liabilities. When leadership fails to track cash conversion cycle mechanics across daily workflows, capital quietly freezes into unsellable pallets, overdue accounts, and sluggish operational handoffs. Every excessive hour spent holding unsold materials or chasing delinquent receivables creates an immediate working capital deficit that must be financed through expensive short-term debt or dilutive equity injections.
Why Paper Profits Mask Looming Liquidity Crises
The standard accrual accounting framework was designed to match operational revenues with their associated expenses, delivering an orderly view of performance over a given period. Unfortunately, accrual conventions can easily disguise creeping liquidity starvation. An accounting system dutifully books revenue the microsecond an invoice prints, recording gross margin and operating profit as accomplished milestones. The bank account, however, remains stubbornly empty until real settlement occurs.
A business can celebrate record quarterly profits while careening into bankruptcy because poorly managed cash conversion cycle mechanics drain the physical liquidity needed to settle vendor bills. When high growth accelerates order volumes, this operational disconnect widens violently. Supplying larger contracts requires purchasing massive quantities of raw inventory upfront, committing immediate funds to manufacturing runs, and funding payroll on strict bi-weekly schedules. If customers demand ninety-day credit terms while raw suppliers demand settlement within thirty days, rapid sales growth accelerates cash depletion rather than generating abundance. In finance, this structural mismatch is known as the growth paradox—an insidious trap where commercial success accelerates operational death.
The 4 Proven Rules That Protect Cash Flow Velocity
Taming these volatile balance sheet forces demands an intimate command of cash conversion cycle mechanics under stressed economic environments. Rather than viewing balance sheet accounts as static balance entries, forward-thinking operators actively tune their operational pulleys to compress working capital drag. The following four operational disciplines systematically reduce time-to-cash while building an impregnable defensive liquidity moat.
Synchronize Inventory Velocity With Unforgiving Demand Pulls
Accumulating buffer inventory feels instinctively safe to risk-averse supply managers, yet idle stock represents rotting balance sheet equity. Storage fees, insurance premiums, shrinkage, and technological obsolescence compound silently with each passing week an item languishes on warehouse racking. Compressing Days Inventory Outstanding requires dismantling speculative production batches in favor of precise, consumption-driven pull models.
Achieving true inventory discipline means analyzing unit-level velocities through rigorous SKU rationalization. High-margin inventory that sits stationary for quarters must be pruned or converted through targeted liquidation channels, freeing trapped liquidity for higher-velocity stock. By coordinating tier-one suppliers around transparent production schedules, procurement teams shrink raw material holding windows from months to days. This rhythmic synchronization ensures production lines receive components moments before assembly, drastically curbing upfront cash commitments without creating supply vulnerabilities.
Restructure Receivables Terms to Accelerate Inbound Capital
Extending generous payment windows to commercial clients is often celebrated by sales teams as a frictionless closing strategy, but it amounts to offering interest-free banking services on the company dime. Compressing Days Sales Outstanding requires replacing passive collection habits with uncompromising credit engineering. Tiered early-settlement discounts—such as two percent off for invoices paid within ten days—frequently generate a massive return by pulling receivables forward and eliminating external borrowing costs.
Equally important is the enforcement of disciplined, automated collections protocols. Invoices must deploy instantly upon service fulfillment, paired with automated ledger reconciliations that flag payment discrepancies on day thirty-one rather than day ninety. Financial managers often ignore the slow-building tension in receivables until payroll bounces, much like how structural pacing and gritty narrative depth in The Lowdown Returns With 4 Major Reasons This Oklahoma Noir Captivates Audiences rely on quiet undercurrents erupting into unavoidable consequence. When financial directors align sales incentives with aggressive cash conversion cycle mechanics, sales teams stop chasing unvetted client accounts that default on ninety-day terms, protecting working capital at its commercial inception.
Negotiate Strategic Vendor Payables Without Burning Supply Chains
Extending Days Payable Outstanding preserves internal cash buffers, but arbitrary supplier payment delays can trigger severe blowback. If an enterprise unilaterally stretches vendor payments from thirty to seventy-five days, critical partners respond by increasing wholesale prices, stripping away priority production slots, or demanding cash on delivery. Ethical payables optimization requires bilateral transparency and strategic negotiation.
Savvy financial leaders negotiate expanded terms by offering contractual volume commitments or predictable purchase visibility in exchange for forty-five or sixty-day settlement windows. Additionally, deploying reverse factoring or supply chain finance arrangements allows suppliers to cash out their receivables immediately through third-party banking partners at institutional rates, while the primary buyer retains sixty-day working capital flexibility. This tactical alignment protects fragile upstream suppliers while preserving enterprise liquidity reserves during cyclical economic contraction.
Deploy Continuous Audits to Eliminate Hidden Cash Leakage
Working capital leaks rarely announce themselves with dramatic fanfare; they fester quietly within disputed billing line items, delayed credit notes, and sloppy shipping authorizations. Establishing permanent cash velocity requires setting up automated weekly telemetry rather than relying on delayed month-end retrospectives. Continuous working capital audits interrogate inventory turnaround variances, uncollected billings, and payment timing differentials in real time.
Cross-functional teams spanning procurement, operational logistics, sales execution, and treasury must review cycle performance weekly. When order-to-cash bottlenecks occur—such as unresolved customer invoicing disputes that freeze multi-million-dollar settlements—operators can intervene immediately to resolve documentation errors before invoices drift into delinquency. Eliminating operational friction within administrative handoffs shaves precious days off working capital cycles, creating self-funding capacity that supports long-term operational initiatives.
Navigating Negative Working Capital Without Risking Supply Chain Ruin
A handful of elite industrial and retail titans accomplish an extraordinary operational feat: running a negative cash conversion cycle. In this rare operational state, a company collects cash from its customers long before it is required to settle accounts with its vendors. Giant retailers and contract manufacturers leverage massive buying power to hold minimal inventory, demand instantaneous point-of-sale customer payment, and negotiate extended ninety-day supplier settlement windows.
Operating on a negative timeline turns cash conversion cycle mechanics into an extraordinary growth engine, but it simultaneously introduces immense operational fragilities. In essence, the enterprise uses its suppliers as an interest-free revolving credit facility to finance customer acquisition, factory expansion, and product development. While this posture generates tremendous returns on invested capital, it operates on razor-thin tolerances. Research on corporate working capital published by the Federal Reserve Board highlights that excessive reliance on supplier credit leaves balance sheets extraordinarily vulnerable during sharp macroeconomic shocks. If sudden consumer demand drops halt point-of-sale cash inflows, an enterprise operating with negative working capital faces immediate payment obligations to suppliers without having collected incoming cash, sparking catastrophic liquidity shortages.
Building Permanent Liquidity Resilience Across Economic Cycles
True business stability is never measured by the valuation multiple an investor assigns during an economic expansion; it is defined by the operational efficiency with which a balance sheet converts commerce into cash. Relying on commercial paper or speculative credit lines to bridge chronic operational cash deficits is a fragile gambit that collapses the moment monetary authorities tighten credit markets. Self-sustaining financial health demands that everyday operations generate sufficient internal liquidity to self-fund their working requirements.
Executive teams that treat cash conversion cycle mechanics as an active engineering discipline rather than a passive accounting metric preserve strategic autonomy when credit lines freeze. By systematically tightening inventory holding intervals, enforcing rigorous customer collection terms, and curating ethical vendor relationships, organizations unlock trapped balance sheet cash without surrendering equity or accumulating high-interest debt. Cash flow velocity is not a byproduct of good fortune; it is the deliberate reward of uncompromising working capital governance.